Qualifying Life Events That Can Trigger a Special Enrollment Period
By Cesar Rincon · 6 min read
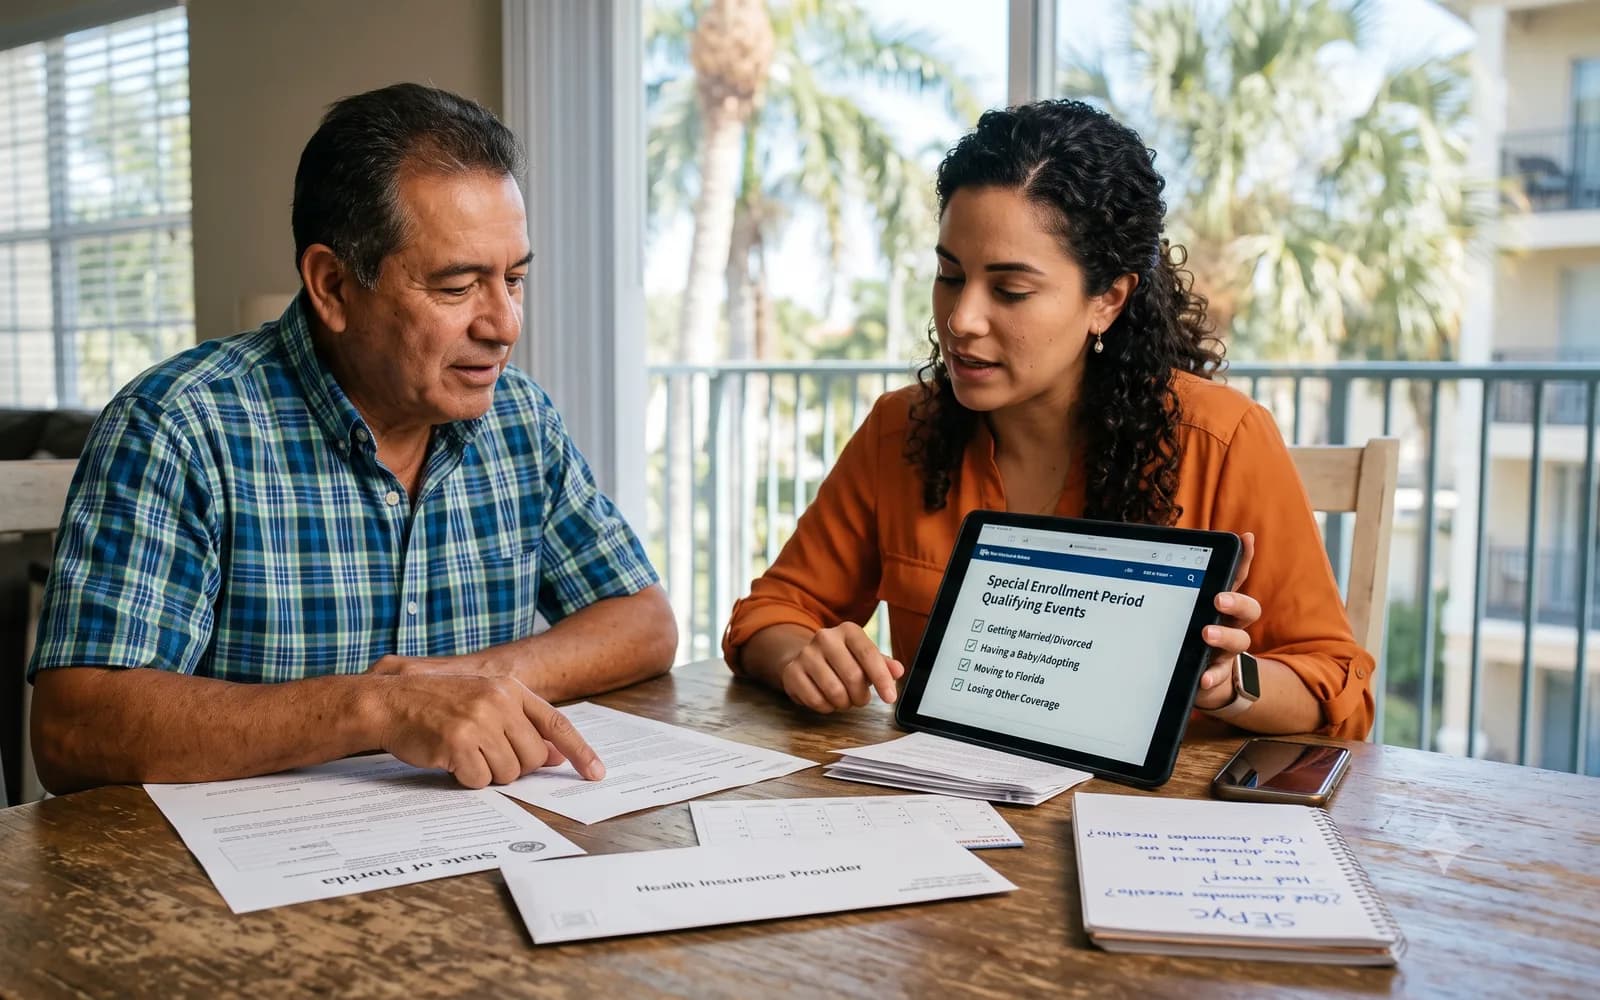
Not every change in your life opens the door to a Special Enrollment Period, but a surprising number of them do. Below is a list of the situations that most commonly qualify — though this isn't a complete or legally exhaustive list, and whether your specific circumstance counts can depend on the details, so it's always worth double-checking your situation rather than assuming either way.
Changes to your household are some of the most common triggers. Getting married is one of the clearest examples, and so is having a baby, adopting a child, or becoming a foster parent. On the other end, a divorce or legal separation that affects your coverage, or the death of someone who was on your policy with you, can also open a window to make changes.
Losing coverage you already had is another major category — and it usually has to be an involuntary loss, not simply canceling a plan because you decided you didn't want it anymore. This includes losing job-based insurance (whether you left the job or your employer stopped offering coverage), aging off a parent's health plan, losing eligibility for Medicaid or CHIP, or reaching the end of COBRA continuation coverage.
Moving can also count, particularly if the move puts you in a new ZIP code or county with a different set of available plans, or if you're moving to Florida from another state. Moves within the same immediate area that don't change your plan options generally don't qualify on their own — the key detail is whether new plans actually become available to you.
There are a handful of other situations worth knowing about, even though they come up less often: gaining U.S. citizenship or another lawfully present immigration status, being released after incarceration, or experiencing domestic violence or spousal abandonment that affects your household's coverage situation. Income changes that affect what subsidies you qualify for can sometimes open a window as well, depending on the specifics.
It's worth being honest about what doesn't count. Simply changing your mind about a plan, forgetting that Open Enrollment happened, or wanting a lower premium isn't, on its own, a qualifying life event. Most of these situations also require documentation — a marriage certificate, a letter from a previous insurer, a lease or utility bill showing your new address — so it helps to know ahead of time what proof you'll likely need.
If one of these situations applies to you, the clock usually starts the day the event happened, not the day you get around to dealing with it. That window doesn't stay open long, so it's worth reaching out sooner rather than later once you know something in your life has changed.
Because eligibility genuinely depends on the details of your situation, this list is meant as a starting point for a conversation, not a final answer. A local, bilingual advisor can help you figure out whether your specific circumstance qualifies and what documentation you'd need to move forward.
Have questions about your specific situation?
Talk to Cesar →