How to Read Your ACA Plan's Summary of Benefits
By Cesar Rincon · 6 min read
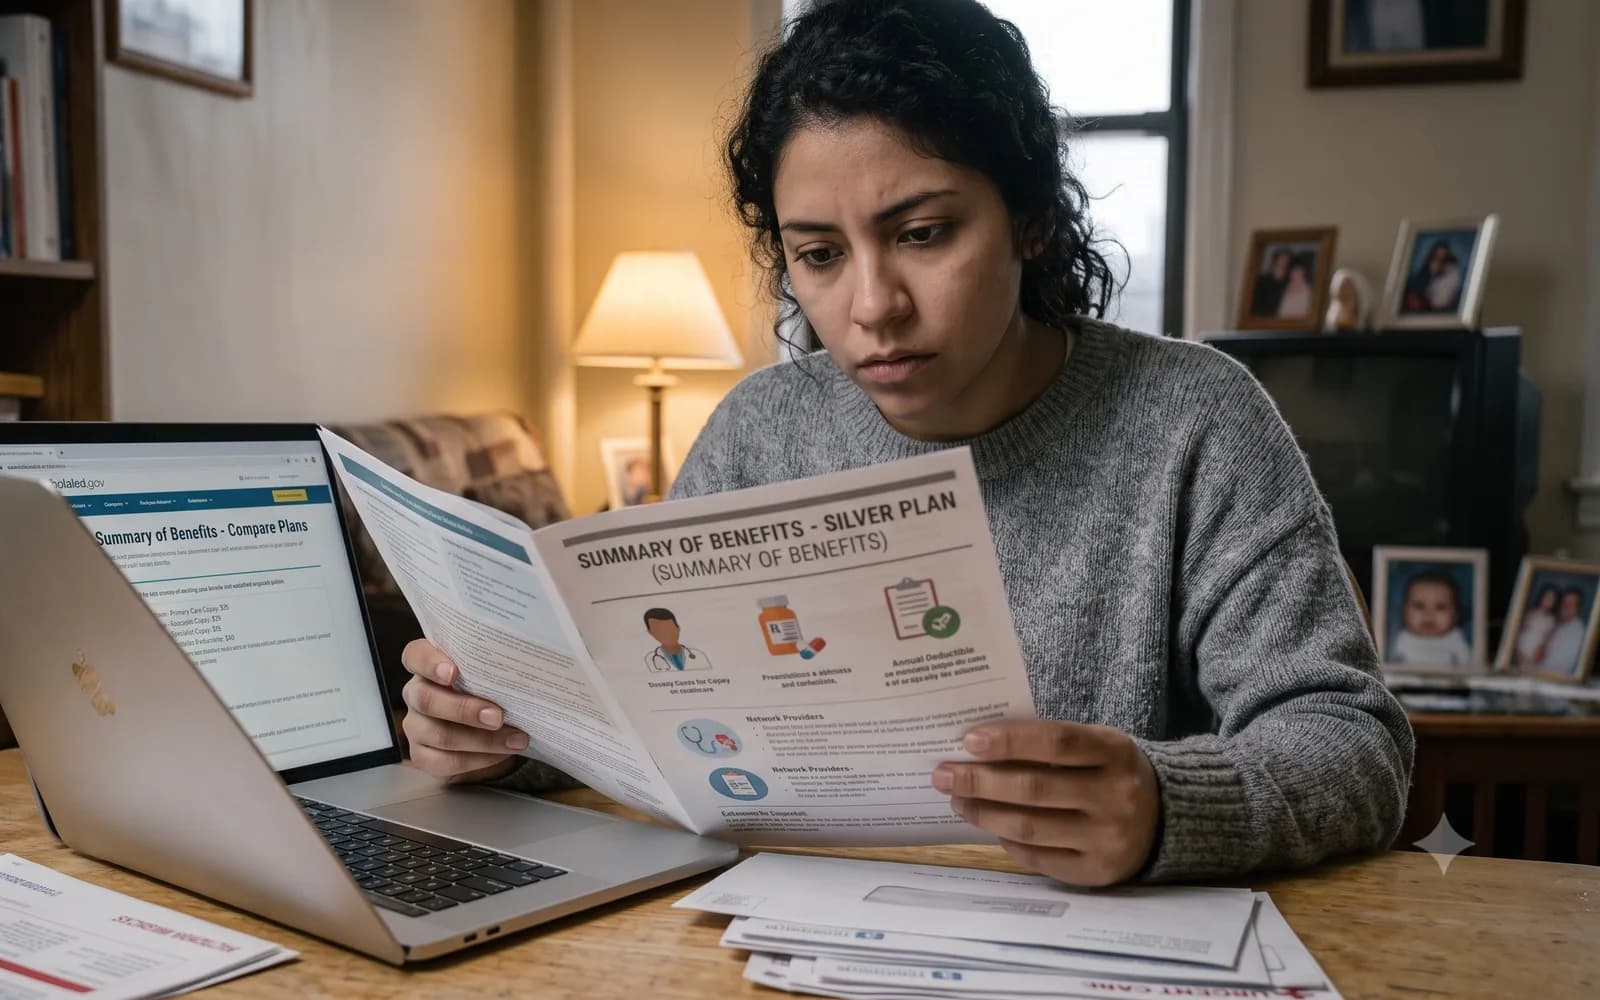
Every ACA plan comes with a standardized document called the Summary of Benefits and Coverage, and even though it can run several pages, you really only need to focus on five sections to understand what a plan actually covers and what it will cost you: the premium, the deductible, the copay/coinsurance structure, the out-of-pocket maximum, and the provider network. Everything else on the document is useful detail, but those five numbers tell you most of the story.
Start with the premium, which is the fixed amount you pay every month just to have the plan, whether you use any care or not. It's the number most people compare first, but it's only one piece of the real cost picture — a plan with a lower premium isn't automatically cheaper once you actually need care.
Next, look at the deductible — the amount you're responsible for paying out of pocket before your plan starts covering most services. Many ACA plans cover certain preventive care, like annual checkups and screenings, before you've met the deductible at all, so it's worth checking that section specifically rather than assuming nothing is covered until the deductible is met.
The copay and coinsurance section is where a lot of confusion happens, but the distinction is simple once you see it laid out: a copay is a flat, predictable amount you pay for a specific type of visit, like a primary care appointment, regardless of what the visit actually costs. Coinsurance, by contrast, is a percentage of the bill you're responsible for after you've met your deductible — so the amount you actually owe depends on how expensive the specific service turns out to be.
The out-of-pocket maximum is arguably the most important number on the whole document, and the one people skip past most often. It's the absolute ceiling on what you'll pay in a given year for covered care — once you hit it, the plan covers 100% of additional covered costs for the rest of the year. This is the number that protects you in a genuinely bad year, like a serious diagnosis or a major surgery.
The provider network section tells you whether the plan is an HMO, PPO, or another structure, which affects whether you need a referral to see a specialist and how much more you'd pay for care outside the network. This section matters just as much as the cost numbers — a plan that looks affordable on paper isn't a good fit if your regular doctors aren't in its network.
One underused part of the Summary of Benefits is the 'coverage examples' section, which walks through what a plan would cost for a couple of common scenarios, like having a baby or managing a chronic condition such as diabetes. Because it uses the same scenario across every plan, it's one of the more genuinely useful ways to compare real-world cost between two plans side by side, rather than just comparing premiums.
Because the specific dollar amounts and coverage details in a Summary of Benefits are tied to a particular plan and plan year, always check the current document for the exact plan you're considering rather than relying on a copy from a previous year or a plan you had before — the numbers are standardized in format, but not identical from plan to plan or year to year.
Have questions about your specific situation?
Talk to Cesar →